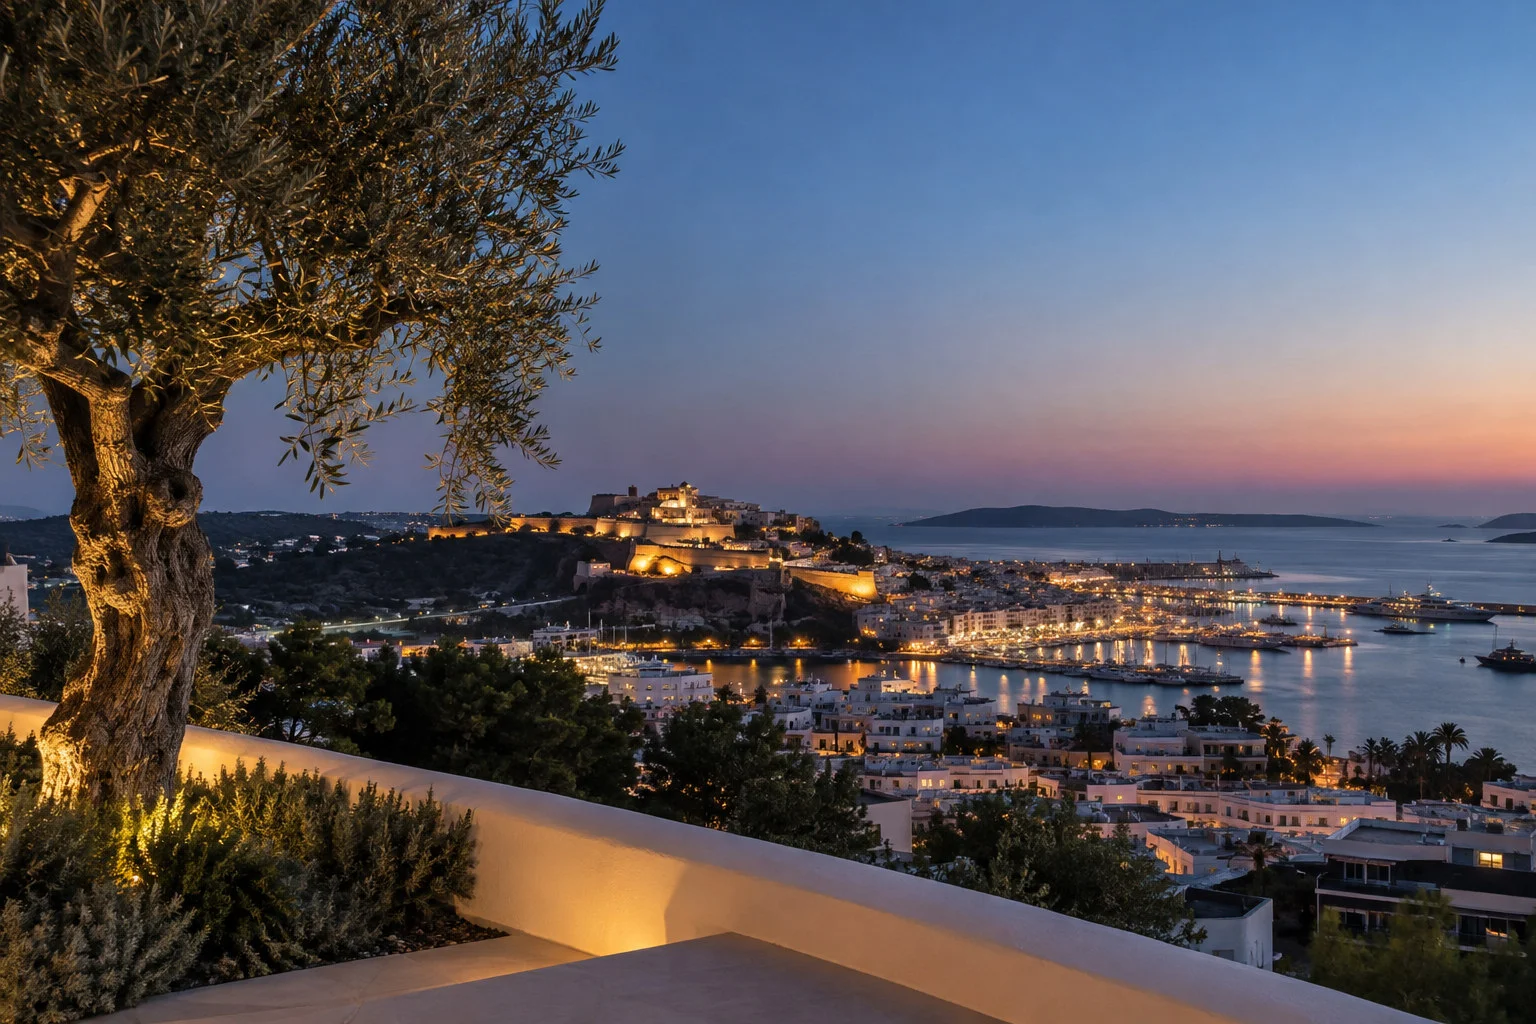
Owning a prime home on Ibiza costs more in tax than in Marbella or Madrid, and the Balearic tax code is the reason. A resale villa pays transfer tax on a scale that reaches 13%. The islands still charge wealth tax, which Andalucía and Madrid have cancelled. Close family, on the other hand, inherit with 100% regional relief, and non-resident heirs can use it. This guide works through every tax an international buyer meets on Ibiza, with worked figures, from the reservation contract to the next generation.
Top ITP band, above EUR 2M
Non-resident wealth-tax allowance
Inheritance relief for close family
Every rate cited to the law
Last updated: October 2026
By: Alexander Thornbury
What tax do you pay to buy a resale home?
ITP, the transfer tax, at 8% to 13% depending on the price. The Balearic scale charges 8% on the first EUR 400,000, 9% to EUR 600,000, 10% to EUR 1M, 12% to EUR 2M and 13% on everything above. The law turns that into a single average rate applied to the whole price, which gives the same answer as working through the bands. Residents and non-residents pay the same, and the tax falls on the higher of the price you declare and the Catastro’s reference value for the property.
At prime levels the effective rate settles between 10% and 12.5%. It rises with the price because the 13% band takes a larger share. Notary and land registry fees come on top but are small next to the tax, and your lawyer’s fee is agreed in advance. Our step-by-step buying guide shows when each payment falls due.
| Price | Resale: ITP | New build: 10% VAT + 2% AJD |
|---|---|---|
| EUR 1.5M | EUR 150,000 (10%) | EUR 180,000 (12%) |
| EUR 2.5M | EUR 275,000 (11%) | EUR 300,000 (12%) |
| EUR 5M | EUR 600,000 (12%) | EUR 600,000 (12%) |
| EUR 10M | EUR 1,250,000 (12.5%) | EUR 1,200,000 (12%) |
Arithmetic on the Balearic ITP scale (Legislative Decree 1/2014, art. 10) and the AJD rate for values of EUR 1M or more (art. 17 bis). Fees not included.
What changes on a new build?
You pay VAT instead of ITP, and a stamp duty on top. VAT on a new home is 10% across Spain. The stamp duty, AJD, is set by the region: in the Balearics it is 1.5% as a rule but 2% once the value reaches EUR 1M, so a prime new build pays a flat 12%. That is more than a resale below EUR 5M and less than one above it, as the table shows. The developer’s first sale of a home is a new-build sale. Any later sale is a resale, however new the house.
One more point applies to resales from a seller who lives outside Spain. You, the buyer, must withhold 3% of the price at completion and pay it to the tax office as an advance on the seller’s capital gains tax. If the seller is a non-resident individual, you also become responsible for the municipal plusvalía tax on the land, so agree with the seller that it is held back from the price too. Both are the seller’s taxes, paid through you.
What does a non-resident pay each year?
Two, before wealth tax: non-resident income tax and the local IBI. If you keep the home for your own use, Spain taxes a notional income of 1.1% of the cadastral value, or 2% where that value has not been revised since 2012. EU and EEA residents pay 19% on it and everyone else 24%. On a cadastral value of EUR 1M that is EUR 2,090 a year for an EU resident and EUR 2,640 for a British or American owner. You file it each year on form 210.
Letting changes the base. EU and EEA residents pay 19% on the net rent after allowable expenses, while others pay 24% on the gross rent. IBI, the municipal property tax, is charged by Eivissa, Santa Eulària des Riu, Sant Josep, Sant Antoni or Sant Joan on the cadastral value, at a rate each council sets.
How much wealth tax will you pay?
More than in Marbella or Madrid. Both of those regions relieve wealth tax, although while the state’s solidarity tax exists they relieve it only down to what that tax would charge. The Balearics charge it in full. A non-resident pays on Spanish assets only, less any debt taken on to buy them, above an allowance of EUR 700,000. The home is valued at the highest of its cadastral value, any value the tax office has set for another tax, and the price you paid, so in the first years the price usually decides it. A return is due if any tax is payable, or if your Spanish assets exceed EUR 2M even when nothing is.
You can choose between two scales. The state scale runs from 0.2% to 3.5%. Where most of your Spanish assets are in the Balearics you can opt for the Balearic scale, 0.28% to 3.45%, but with the same EUR 700,000 allowance the state scale works out lower at every level a buyer is likely to meet. The Balearic scale would only pay if you could also claim its EUR 3M allowance, and that allowance is written for Balearic residents. Take advice before relying on it. The solidarity tax, which starts on taxable wealth above EUR 3M after its own EUR 700,000 allowance, deducts the wealth tax you have paid, and as the wealth tax is always the larger, an Ibiza owner normally owes none. The same owner in Marbella or Madrid pays wealth tax only up to the solidarity-tax amount, which is why the gap in the table is so wide.
| Non-resident, EUR 5M net Spanish assets (2026) | Ibiza, state scale | Ibiza, Balearic scale | Marbella or Madrid |
|---|---|---|---|
| Allowance | EUR 700,000 | EUR 700,000 | EUR 700,000 |
| Taxable wealth | EUR 4.3M | EUR 4.3M | EUR 4.3M |
| Wealth tax a year | About EUR 53,500 | About EUR 73,500 | About EUR 22,100, the solidarity-tax amount |
| Solidarity tax after deducting wealth tax | Nil (EUR 22,100 before the deduction) | Nil | Nil |
Arithmetic on the state scale (Law 19/1991, art. 30), the Balearic scale (Legislative Decree 1/2014, art. 9) and the solidarity tax scale (Law 38/2022, art. 3), with no other Spanish assets or debts. Marbella and Madrid: the regional relief while the solidarity tax applies (Agencia Tributaria, Wealth Tax manual 2025), assuming you opt for the regional rules.
How is a sale taxed?
At 19% on the gain, for every non-resident, EU or not. The gain is the sale price less what you paid, including the purchase taxes and the cost of improvements you can document, less the costs of selling. The 3% your buyer withholds counts towards the bill, and you file a return to settle the balance or reclaim the excess. Then comes the municipal plusvalía on the increase in the land’s value, which the seller owes.
Your home country may tax the same gain. Most of Spain’s treaties give Spain the first right to tax property in Spain, and your own country then credits the Spanish tax or exempts the gain, depending on the treaty. The detail is set out for each country in our guides for buyers from the UK and the Netherlands, among others listed in our main Ibiza guide.
What happens on death?
For close family, Balearic inheritance tax is effectively nil. Since July 2023, heirs in Groups I and II, meaning children and grandchildren, spouses and parents, receive a 100% regional relief on the tax. Since 2025, siblings, nephews, nieces, uncles and aunts receive 60% where they don’t inherit alongside the deceased’s own descendants, and 35% where they do. The relief has conditions. The value declared for the property can’t exceed its Catastro reference value by more than 20%, and a return must still be filed.
Non-resident families can use these rules. When the person who died lived outside Spain, the heirs apply the law of the region that holds the greatest value of their Spanish assets, which for an Ibiza villa is the Balearics. That right followed a 2014 ruling of the EU Court of Justice, and it now applies to heirs from any country. Your home country’s inheritance tax is a separate matter, as is the law that governs the will: under the EU Succession Regulation it is the law of your habitual residence at death, unless you choose the law of your nationality. Our residency guide explains how moving to the island changes the picture, and our comparison with Mallorca and Marbella sets the regional rules side by side.
| Balearic inheritance tax (2026) | Regional relief |
|---|---|
| Children, grandchildren, spouses, parents (Groups I and II) | 100% since July 2023 |
| Siblings, nephews, nieces, uncles, aunts, not inheriting with descendants | 60% |
| Other Group III heirs | 35% |
| Unrelated heirs (Group IV) | No regional relief |
Key takeaways
- Resale ITP runs from 8% to 13%, which makes 10% to 12.5% of the price at prime levels.
- A prime new build pays a flat 12%: 10% VAT plus 2% stamp duty from EUR 1M.
- Wealth tax is the main running cost. Non-residents pay above EUR 700,000: about EUR 53,500 a year on EUR 5M, against about EUR 22,100 in Marbella or Madrid.
- The solidarity tax is normally nil, because the wealth tax paid is deducted from it.
- Close family inherit with 100% relief, and non-resident heirs can claim it.
- A non-resident seller pays 19% on the gain, with 3% withheld by the buyer.
Frequently asked questions
What is the transfer tax on a resale home in Ibiza?
The Balearic ITP: 8% to EUR 400,000, 9% to EUR 600,000, 10% to EUR 1M, 12% to EUR 2M and 13% above. On a EUR 5M villa that comes to EUR 600,000, or 12%. It is charged on the higher of the price and the Catastro reference value.
Do non-residents pay more transfer tax than residents?
No. The Balearic ITP scale is the same for every buyer. The difference for non-residents comes later, in income tax on the home and in the wealth-tax allowance.
What tax applies to a new-build villa?
VAT at 10% and stamp duty (AJD) at 2% where the value is EUR 1M or more, so 12% in all. Below EUR 1M the stamp duty is 1.5%.
Is new build or resale cheaper in tax?
It depends on the price. Below EUR 5M a resale pays less, because the average ITP rate is under 12%. Above EUR 5M a new build pays less, because the resale rate keeps climbing towards 13%.
Does a non-resident pay wealth tax on an Ibiza home?
Yes. The Balearics have not cancelled wealth tax. A non-resident pays on net Spanish assets above EUR 700,000, at 0.2% to 3.5% on the state scale, which is normally cheaper than the Balearic scale for a non-resident.
How is the villa valued for wealth tax?
At the highest of three figures: the cadastral value, any value the tax office has set for another tax, and the price you paid. For a recent purchase that usually means the price. Debt taken on to buy it is deducted.
Will I also pay the solidarity tax on large fortunes?
Normally not. The solidarity tax deducts the wealth tax already paid, and where wealth tax is charged in full, as in the Balearics, it is always the larger. On EUR 5M of net Spanish assets the solidarity tax would be EUR 22,100 before the deduction and nil after it.
What income tax does a non-resident owner pay if the home is not let?
Non-resident income tax on a notional 1.1% of the cadastral value, or 2% if the value has not been revised since 2012, at 19% for EU and EEA residents and 24% for others. You file it every year on form 210.
How much capital gains tax does a non-resident pay on selling?
19% on the gain, whatever your nationality. The buyer withholds 3% of the price for the tax office, and you settle the balance on a return. The municipal plusvalía on the land is also the seller’s to pay.
Is there inheritance tax on an Ibiza property?
Not for children, grandchildren, spouses or parents, who have had 100% Balearic relief since July 2023. Siblings, nephews and nieces get 35% or 60%. Non-resident heirs can apply these rules where the deceased lived outside Spain.
Should I buy an Ibiza villa through a company?
Not through one based in a tax haven: Spain charges such companies a special tax of 3% of the property’s cadastral value every year. Any company structure changes the income, wealth and inheritance picture, so take advice on the whole of it before you sign.
Can I avoid Spanish forced heirship on an Ibiza home?
Usually there is nothing to avoid. Under the EU Succession Regulation the estate follows the law of your habitual residence at death, so a non-resident’s estate follows their home country’s law by default. Choosing the law of your nationality in your will keeps it that way if you later move to Ibiza.
Sources
- BOE – Balearic Legislative Decree 1/2014 on ceded taxes, consolidated text (ITP art. 10; stamp duty arts. 15 and 17 bis; wealth tax arts. 8 and 9; inheritance relief arts. 36 and 36 bis)
- BOE – Transfer Tax Act, Royal Legislative Decree 1/1993 (tax base and reference value)
- BOE – VAT Act, Law 37/1992 (10% on new homes)
- BOE – Non-Resident Income Tax Act, Royal Legislative Decree 5/2004 (imputed income, rental income, capital gains, 3% withholding, 3% special tax on tax-haven companies arts. 40-43)
- BOE – Local Finance Act, Royal Legislative Decree 2/2004, art. 106 (plusvalía: buyer as substitute taxpayer for non-resident sellers)
- BOE – Wealth Tax Act, Law 19/1991 (valuation art. 10, scale art. 30, filing art. 37, non-residents additional provision 4)
- Agencia Tributaria – Wealth tax for non-residents (EUR 700,000 allowance, deductible debts)
- Agencia Tributaria – Wealth Tax practical manual 2025 (regional rules for all non-residents; Andalucía and Madrid reliefs while the solidarity tax applies)
- BOE – Law 38/2022, article 3 (solidarity tax on large fortunes)
- BOE – Inheritance and Gift Tax Act, Law 29/1987 (additional provision 2, non-resident heirs)
- EUR-Lex – EU Succession Regulation 650/2012
Figures current at October 2026. Balearic tax rates can change with each regional budget, usually from 1 January, and should be confirmed with a Spanish tax adviser at the point of purchase.
About the author
Alexander Thornbury is a published author who writes on international property, tax and residency for high-net-worth buyers across Europe. His work focuses on the practical mechanics of cross-border purchase: what a buyer actually pays, owes and signs. More at alexanderthornbury.com.